 Physix Frontier

Nearly 25,000 Humanoid Robots Shipped in Half a Year—Where Did 69% Go?

October 5, 2026
Global humanoid robot shipments in the first half of the year approached 25,000 units, up 432.1% year-on-year. Chinese manufacturers contributed over 95% of shipments. This is IDC's H1 2026 statistics released on September 29, and China's hardware delivery advantage is already quite clear.
But in the same report, there's another number that's easy to overlook because of the growth rate. Research and education, performance and display, and government data collection centers together account for 69% of shipments.
This means that to understand this round of growth, we need to keep looking at where the robots are going. Selling to labs and using them to collect training data is different from entering stores and factories to generate operating revenue — the reasons customers pay are different, and the conditions for the next purchase are different too.
Chinese companies have already delivered humanoid robots to customers in bulk. The next question to answer is: why would these customers buy another batch?
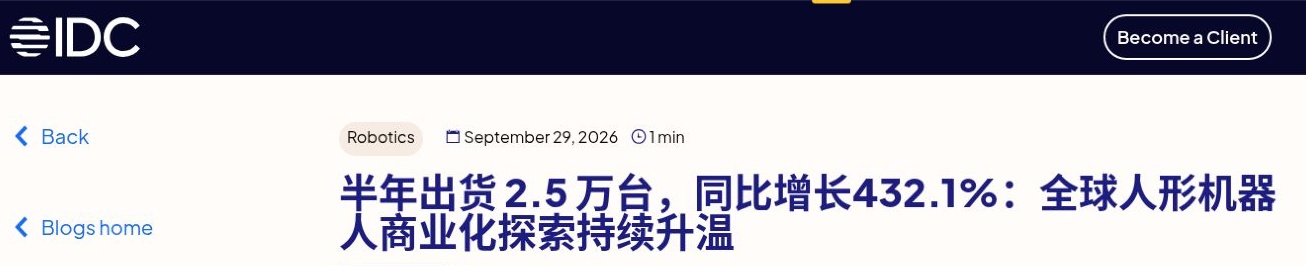
IDC official website, September 29, 2026. The nearly 25,000 units statistic covers H1 2026 shipments.
Behind the 69% are three different businesses
Research institutions buy robots for algorithm development and teaching; buyers of performance and display robots value interactivity and the ability to attract audiences; data collection centers buy robots to collect motion data and train robot models. They all have specific uses and may generate real revenue.
So 69% can't be directly translated as "no commercial value." A lab buying a development platform never needed it to replace assembly line workers. A scenic spot buying performance equipment should also be evaluated by visitor experience and operating revenue.
What really needs to be prevented is understanding all these shipments together as robots already replacing human work at scale. Shipment statistics answer how many devices were delivered; only customer operating records can answer what the devices created.
Another change IDC gives is equally important. The share of the above three scenarios dropped from 83.8% for all of 2025 to 69% in H1 2026. The combined share of the remaining scenarios rose correspondingly from 16.2% to 31%.

IDC official website, September 29, 2026. The 69% is composed of research and education, performance and display, and government data collection centers combined; the comparison base period is full-year 2025.
This is a sign of demand structure expansion. However, it compares a full previous year with half of this year, so it can't be treated as a strict same-period comparison; the remaining 31% also includes multiple uses, and can't all be counted as industrial production, let alone profitable deployments.
For investors, the explanation of growth thus becomes more specific. Beyond existing procurement, robots are finding new reasons to be paid for, and the prices, service costs, and repurchase cycles that different reasons can support may differ greatly.
After 8,600 units, look at one store case
AgiBot cited IDC data on its official website on September 30, disclosing H1 humanoid robot shipments of over 8,600 units, about 35% global share. This is enough to show it already has considerable delivery capability.
To continue understanding the commercial results, we can look at another more specific disclosure from the company.
AgiBot's official website published ASD cooperation materials stating that 100 Lingxi X2 units entered 100 stores; from September 28 to 30, stores in Wenling, Shanghai, and Wuxi conducted livestreams for three consecutive days, 10 hours per day.
The robots took on tasks like greeting, asking about needs, introducing products, and recommending cookware. The materials also clearly state that promotion, inventory, and the final purchase step need to be completed in collaboration with store staff.
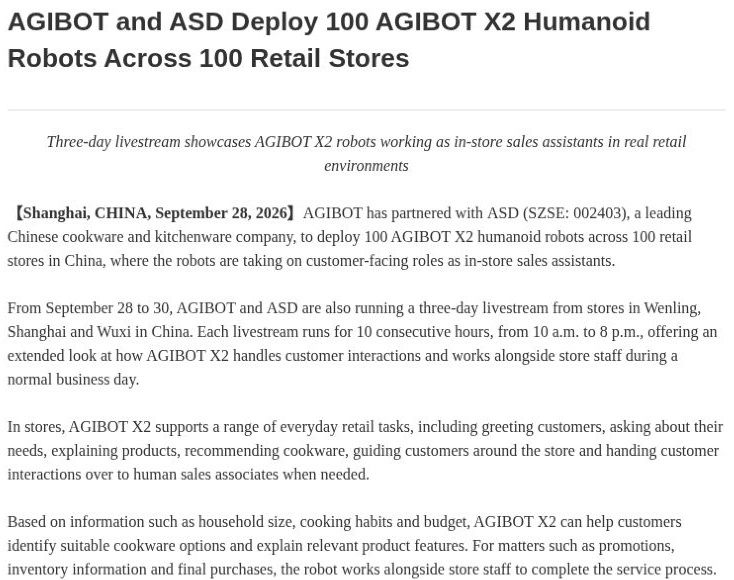
AgiBot official website, internal date September 28, 2026. Deployed 100 units, and clearly states promotion, inventory, and final purchase require staff collaboration.
This boundary is very informative. At the current stage, retail deployment can start with reception and product explanation, while staff continue to handle transactions. When evaluating it, we should look at how much revenue this division of labor added to the store, and how much maintenance and collaboration work it added.
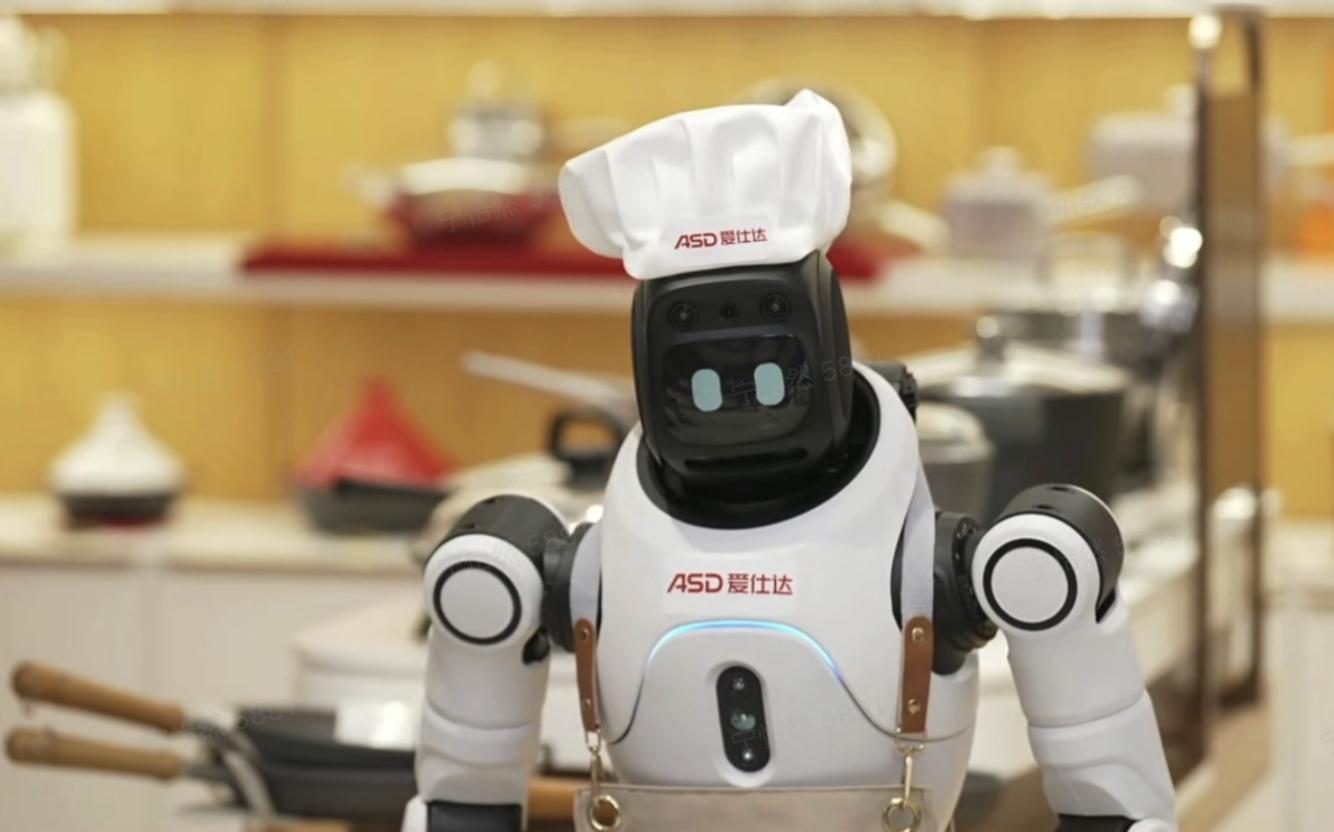
Actual store photo of Lingxi X2 provided by AgiBot's official website. The image shows the deployment scenario and cannot alone prove transaction improvement or investment payback period.
The above materials are the company's deployment disclosure and cannot yet prove that all 100 stores completed continuous operation assessment. The three-day livestream also didn't give comparable transaction improvement, labor input changes, failure rates, or investment payback period.
But it provides a trackable sample. Whether ASD expands deployment next time, and whether it's willing to disclose usage results, is closer to the customer's business judgment than how many sentences the robot said in one livestream.
How does mass production leadership turn into profit
Chinese manufacturers' over 95% shipment share shows that supply is currently highly concentrated in Chinese companies. China's market accounts for about 77.9% of global shipments, which describes the regional destination of equipment sales. The two ratios have different denominators, cannot substitute for each other, and cannot be used to directly calculate export volume by subtraction.
The commercial value of manufacturing advantage ultimately has to pass through the customer usage link.
When a robot is sold, the OEM may get a one-time equipment revenue. For the customer to integrate it into daily work, deployment, training, maintenance, and handling exceptions are still needed. If every additional store requires a large investment of on-site engineers, shipment expansion will simultaneously bring service cost expansion.
Conversely, if the same product and process can be reused in more stores, and remote maintenance can solve most problems, then the cost of new deployments has a chance to decline. This is a commercial condition derived from the deployment method, and one cannot conclude that a company has already achieved it based only on shipment rankings.
Lower hardware costs certainly help, but customers also need to calculate total expenditure during use. Procurement or leasing fees, repairs, software services, and the labor still required should all be compared together with the actual increased revenue or saved costs.
Factory customers look at cycle time and yield rate; store customers look at reception effectiveness and transactions. For this batch of ASD stores, the most convincing evidence is comparable operating changes, and repeat purchases that happen after those changes.
This also explains why capacity expansion news can't be directly converted into profit. Planned capacity must be converted into actual production, products must be delivered and meet contract acceptance conditions, and revenue recognition and payment collection each have their own timing. Every step needs its own evidence.
An independent observation provides a reminder. A Reuters investigation report on August 27 mentioned that a robot training center in Liuzhou hoped to sell training data, but interviewed staff said high operating costs and low data prices left the project's profit path still unclear.
This case can't represent the entire industry. The boundary it illustrates is that equipment being purchased and the business after purchase being able to continuously make money can be at different stages at the same time.
The next batch of orders will give a clearer answer
The decline in the 69% share already shows shipment uses are expanding. Next, three specific things are worth watching.
First, under the same statistical scope, whether shipments outside research and education, display, and data collection can continue to grow, and disclose finer uses. Share changes and absolute numbers should be looked at together.
Second, look at the follow-up records of this batch of ASD stores. Whether they continue operating, how much collaboration time staff need to invest, and whether customers expand procurement can all help judge the value of deployment. If verifiable operating improvements and repeat paid orders appear, the judgment on commercialization can be more positive.
Finally, look at the OEM's financial disclosures. Whether revenue growth is accompanied by gross margin improvement, whether deployment and after-sales costs are controllable, and whether payment collection keeps up with delivery. These numbers can test whether bulk sales are turning into a sustainable business.
Nearly 25,000 units in half a year is the hardware score already delivered. The next more weighty score will be whether customers are willing to keep paying after using them.

