 Physix Frontier
Nearly 25,000 Humanoid Robots Shipped in Half a Year: Where Did 69% Go?
October 5, 2026
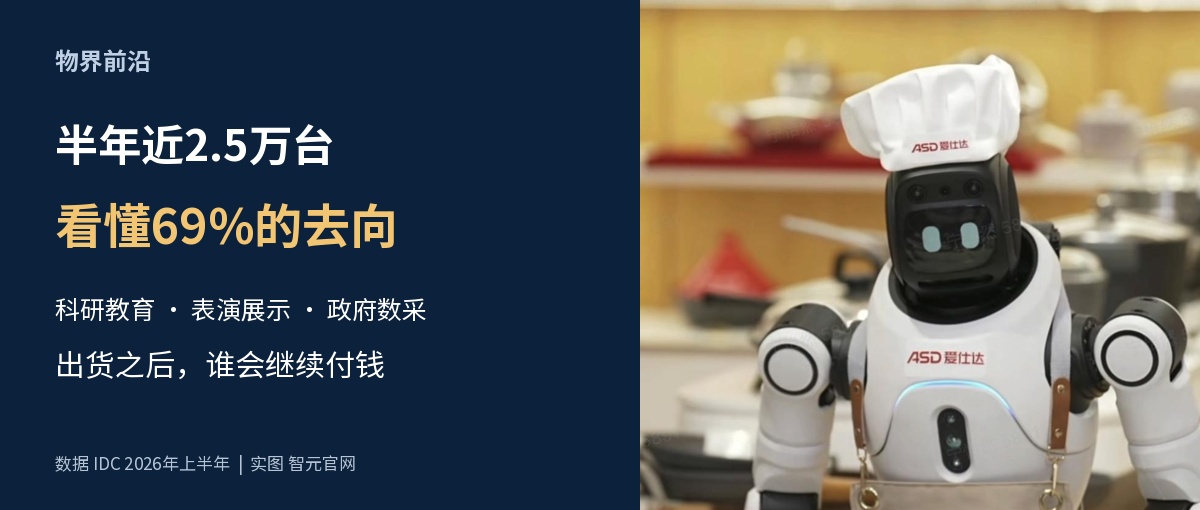
Global humanoid robot shipments in the first half of the year approached 25,000 units, up 432.1% year over year. Chinese manufacturers contributed more than 95% of shipments. This is IDC's statistics for the first half of 2026 published on September 29, and China's hardware delivery advantage is already quite clear.
But in the same report, there is another number that is easily overshadowed by the growth rate. Scientific research and education, performance and display, and government data collection centers together accounted for 69% of shipments.
This means that to understand this round of growth, one needs to keep looking at where the robots are going. Selling to laboratories and using them to collect training data is different from entering stores and factories to generate operating income: customers pay for different reasons, and the conditions for the next purchase are also different.
Chinese companies have already delivered humanoid robots to customers in batches. The next question to answer is: why would these customers buy another batch?
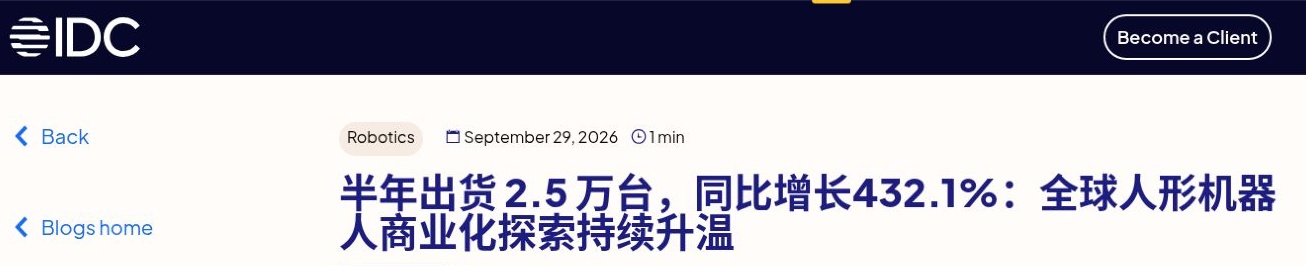
IDC official website, September 29, 2026. The nearly 25,000 units statistic refers to shipments in the first half of 2026.
Behind 69% Are Three Different Businesses
Research institutions buy robots that can be used for algorithm development and teaching; buyers for performance and display value their ability to interact and attract audiences; data collection centers buy robots to collect motion data and train robot models. All have specific uses and may also generate real revenue.
Therefore, 69% cannot be directly translated into "no commercial value." A laboratory purchasing a development platform does not originally need it to replace assembly line workers. A scenic area purchasing performance equipment should also be evaluated based on visitor experience and operating returns.
What really needs to be prevented is understanding all these shipments together as robots already replacing human work on a large scale. Shipment statistics answer how many devices were delivered; customers' operating records can answer what the devices created.
Another change given by IDC is equally important. The share of the above three types of scenarios fell from 83.8% for all of 2025 to 69% in the first half of 2026. The combined share of the remaining scenarios rose correspondingly from 16.2% to 31%.

IDC official website, September 29, 2026. The 69% is composed of scientific research and education, performance and display, and government data collection centers combined; the comparison base period is full-year 2025.
This is a sign of demand structure expansion. However, it compares the previous full year with the first half of this year, so it cannot be treated as a strict year-over-year comparison; the remaining 31% also includes multiple uses, cannot all be counted as industrial production, and even less as already profitable deployments.
For investors, the explanation of growth therefore becomes more concrete. Beyond existing procurement, robots are seeking new reasons to be paid for, and the selling price, service cost, and repurchase cycle that different reasons can support may differ greatly.
After 8,600 Units, Look at a Store Case
AgiBot cited IDC data on its official website on September 30, disclosing that humanoid robot shipments in the first half of the year exceeded 8,600 units, with a global share of about 35%. This is enough to show that it already has considerable delivery capability.
To continue understanding the commercial results, one can look at another more specific disclosure from the company.
AgiBot's official website published cooperation materials with ASD stating that 100 Lingxi X2 units entered 100 stores; from September 28 to 30, stores in Wenling, Shanghai, and Wuxi conducted live streams for three consecutive days, 10 hours per day.
The robots took on tasks such as greeting customers, asking about needs, introducing products, and recommending cookware. The materials also clearly state that promotion, inventory, and the final purchase step need to be completed in collaboration with store staff.
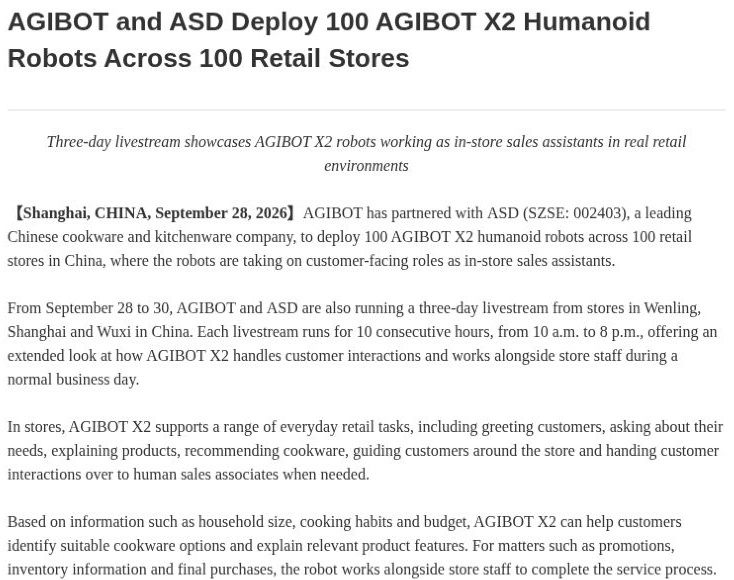
AgiBot official website, internal date September 28, 2026. 100 units deployed, and it explicitly states that promotion, inventory, and final purchase require staff collaboration.
This boundary is very informative. At the current stage, retail deployment can start with reception and product explanation, while store staff continue to handle transactions. When evaluating it, one should look at how much revenue this division of labor adds to the store, and how much maintenance and collaboration work it adds.
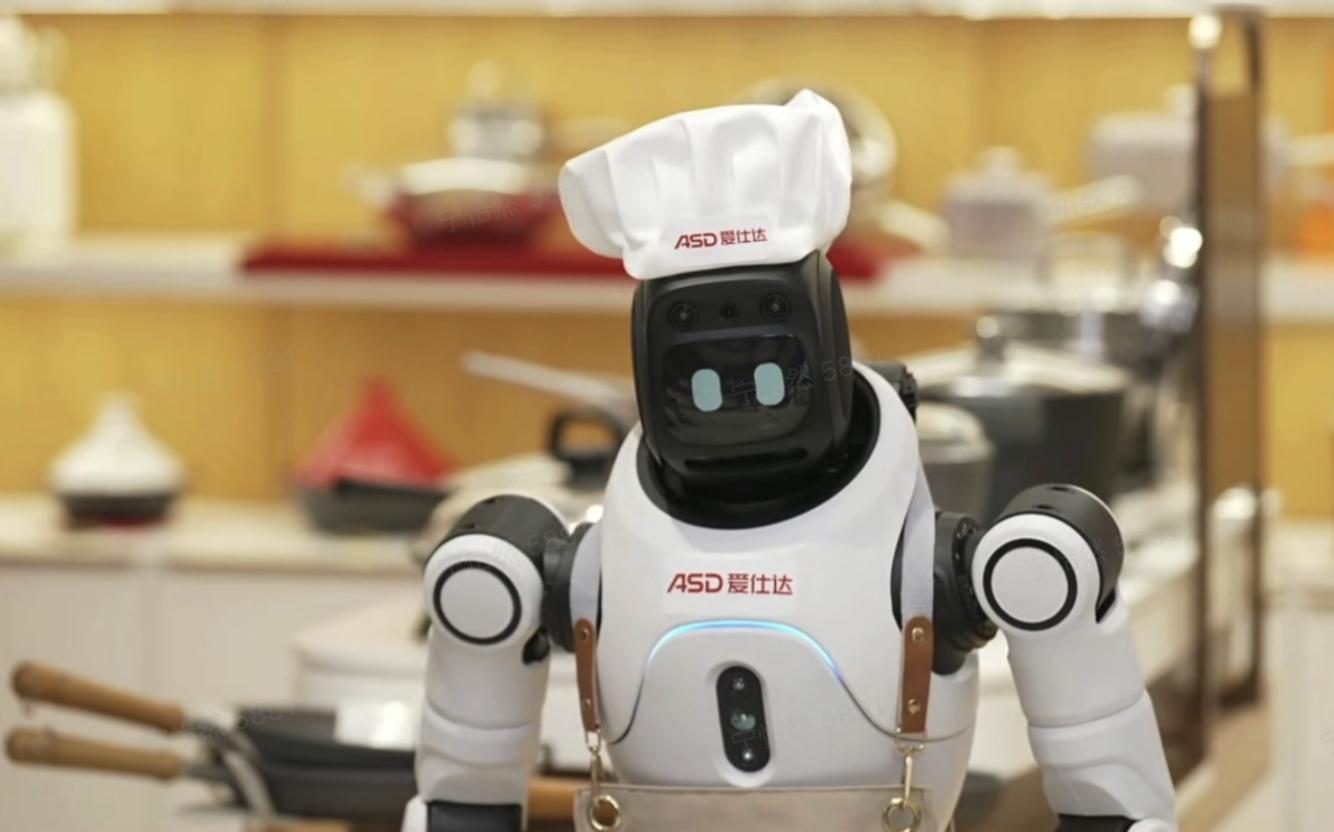
A real store photo of Lingxi X2 provided by AgiBot's official website. The image shows the deployment scenario and cannot by itself prove transaction improvement or investment payback period.
The above materials are the company's deployment disclosure and cannot yet prove that all 100 stores completed continuous operation assessments. The three-day live stream also did not provide comparable transaction improvement, changes in labor input, failure rate, or investment payback period.
But it provides a traceable sample. Whether ASD expands deployment next time, and whether it is willing to disclose usage results, is closer to the customer's business judgment than how many sentences the robot said in one live stream.
How Does Mass Production Leadership Turn into Profit?
Chinese manufacturers' shipment share of more than 95% shows that current supply is highly concentrated among Chinese companies. China's market accounts for about 77.9% of global shipments, which describes the regional destination of equipment sales. The two ratios have different denominators, cannot substitute for each other, and cannot be used to directly calculate export volume by subtraction.
The commercial value of manufacturing advantage ultimately still has to pass through the customer usage stage.
When a robot is sold, the OEM may receive a one-time equipment revenue. For the customer to integrate it into daily work, deployment, training, maintenance, and handling exceptions are still needed. If every additional store requires a large number of on-site engineers, shipment expansion will simultaneously bring service cost expansion.
Conversely, if the same product and process can be reused in more stores and remote maintenance can solve most problems, then the cost of additional deployment can